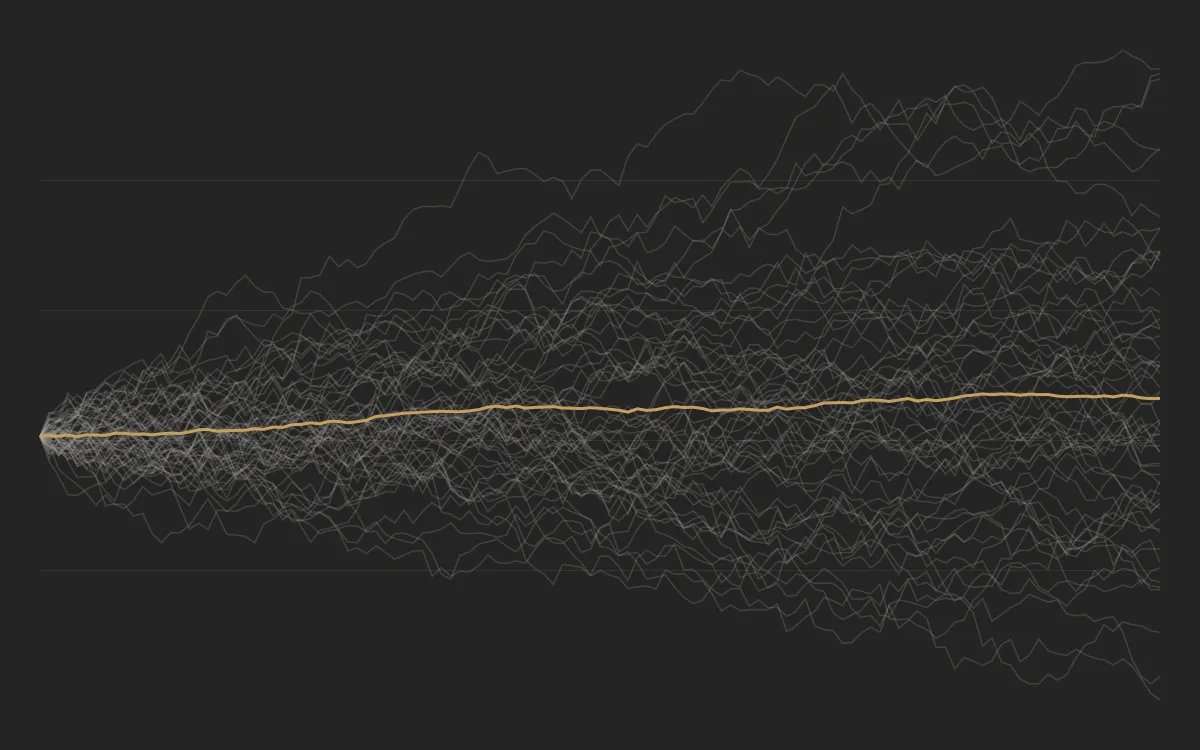
Planned. Pricing European options by simulating many price paths, then checking how quickly the estimate converges to the Black–Scholes price.
Aug 2026·in progress·Python · NumPy
This one is still in the works. The idea is simple: simulate a large number of price paths, average the discounted payoff, and see how close the estimate gets to the closed-form price,
V^=e−rTN1i=1∑Nmax(ST(i)−K,0).
The full write-up, with results and limitations, will go here once it’s done.